For decades, one credit scoring model has decided who gets a mortgage and what they pay for it. That era is officially ending. The Federal Housing Finance Agency, under Director William J. Pulte, has directed Fannie Mae and Freddie Mac to accept VantageScore 4.0 from every mortgage lender that sells them loans, effective immediately. The Federal Housing Administration is following close behind, with FHA lenders able to use the model starting January 1, 2027.
This is one of the most significant changes to mortgage qualifying in a generation. It could open the door to homeownership for millions of people who pay their bills on time every month but have never had a traditional credit score that shows it.
The change has come together in a series of steps over the past several months.
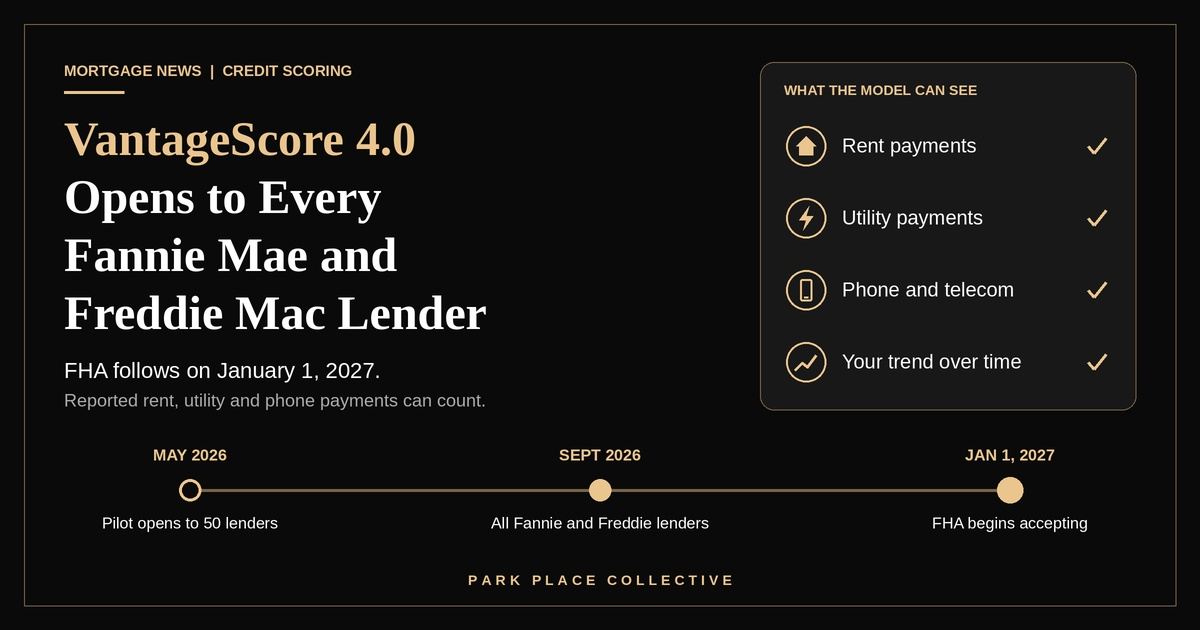
Spring 2026: a limited rollout. FHFA and HUD announced the implementation plan in April, and Fannie Mae and Freddie Mac began accepting loans scored with VantageScore 4.0 on May 1 through a pilot limited to 50 lenders. Adoption moved faster than expected. By August 31, VantageScore 4.0 was the only credit score used on more than 9% of all loans the two agencies securitized since the pilot began.
September 2026: every lender. In early September, Director Pulte instructed Fannie Mae and Freddie Mac to approve all lenders to use VantageScore 4.0, removing the 50 lender cap. Days later, FHFA announced that every mortgage backed security and credit risk transfer issued by the two agencies will disclose a VantageScore 4.0 score alongside the legacy score, giving investors the data they need to price these loans with confidence.
January 1, 2027: FHA joins. FHA announced that for case numbers assigned on or after January 1, 2027, lenders can use VantageScore 4.0 and FICO Score 10T in addition to Classic FICO on eligible forward mortgages. FHA loans make up nearly one in five mortgages in the country, so this extends the change well beyond conventional lending.
Traditional mortgage scoring leans heavily on credit cards, auto loans and student loans. If you have paid rent for ten years without missing a month, that history has often been invisible. VantageScore 4.0 is built to use rental, utility and telecommunications payment data when it appears on your credit report. For renters who have been responsible for years, that is a real change in how lenders see them.
VantageScore 4.0 uses what the industry calls trended data. Instead of only asking what your balances are today, it looks at how your credit behavior has moved over time. Someone who has been steadily paying down balances looks different from someone whose balances keep climbing, even if both have the same balance on the day the report is pulled. That rewards the habits that actually predict whether someone repays a mortgage.
According to VantageScore, its model can score roughly 33 million more adults than traditional models, including close to 5 million people who are ready for a mortgage but could not be evaluated before. Many of these are people with thin files or credit that has simply gone quiet, not people with bad credit. The National Association of REALTORS has long pushed for modernized scoring for exactly this reason: it widens the path to homeownership, especially for buyers with limited credit histories.
When one company controls the only accepted score, there is little pressure on price. Director Pulte has pointed directly to the steep rise in credit score costs in recent years as a reason for opening the market. VantageScore cites an independent study estimating more than $930 million in savings across the mortgage market in the first year. Credit report and scoring fees end up in borrower closing costs, so more competition is good news for anyone financing a home.
First time buyers and younger adults who have rented for years but carry little traditional debt are the most obvious winners. So are self employed borrowers and gig workers who have kept their finances simple, people rebuilding after a hardship who now have a solid recent track record, and households that intentionally avoid credit cards. VantageScore also highlights rural Americans, veterans and active duty service members as groups the model can help reach.
This is a big step forward, but it is important to understand the fine print so expectations stay realistic.
Lenders choose which score to use. All lenders are now permitted to use VantageScore 4.0 for Fannie Mae and Freddie Mac loans, but each lender still has to complete agency and vendor setup, and not every lender will adopt it at the same pace. Reporting also indicates Classic FICO continues to accompany loans delivered to the agencies for now.
FHA rules still apply. FHA is keeping its three bureau credit report requirement and its existing minimum score thresholds. The new models are added as options alongside Classic FICO, not as a replacement.
Alternative data only helps if it is reported. Your rent and utility history can only count if it actually shows up on your credit report. Many landlords and utility companies do not report automatically.
A score is not the whole approval. Income, debt to income ratio, assets, employment and the property itself still matter. A better score opens doors. It does not replace the rest of the file.
If you are thinking about buying in the next year, start positioning yourself today. Pull your free reports from all three bureaus at AnnualCreditReport.com and dispute anything that is wrong. Ask your landlord or property manager whether they report rent payments, and if they do not, look into a reputable rent reporting service. Keep every utility, phone and internet bill current, since those payments may soon work in your favor. Avoid opening new accounts or taking on new debt before you apply, and keep credit card balances low and trending down.
Most importantly, work with a mortgage professional who can shop your file across multiple lenders. Because lenders will adopt VantageScore 4.0 on different timelines, access to many lenders matters more than ever. As an independent mortgage brokerage, Park Place Collective can compare lenders to find the ones that will evaluate your file using the model that best reflects your real financial picture.
For years, responsible renters and careful savers have been told they did not have enough credit to buy a home. VantageScore 4.0 opening to every Fannie Mae and Freddie Mac lender, with FHA following in January, changes that conversation. The system is starting to recognize the payments people make every month, and that could put homeownership within reach for millions of Americans.
If you have been waiting on the sidelines because of your credit, now is the time to find out where you stand. Reach out to the Park Place Collective Team for a no obligation review of your credit and your buying options.
PARK PLACE COLLECTIVE
Mortgage | Real Estate | Life Insurance
Email jcosta@parkplacefg.com | Office 619-990-7552 | Cell 646-245-7856
NMLS 2571108 | DRE 02230476 | DFPI 60DBO-212395 | Joe Costa NMLS 113396, DRE 01410823 | Marni Costa DRE 01858497 |
Mortgage Broker AZ, CA, CO: NMLS 2571108, Colorado ER. 10009916, CA DFPI 60DBO-212395.
This article is for general information only and is not a commitment to lend. Credit model availability, program guidelines and approval depend on the lender and are subject to change